

Today I want to introduce you to a stock that IPO’d only a few months ago, already has 67 million accounts, is growing revenues at 85% year-over-year, and yet trades at roughly 9–10x trailing earnings. The company is PicPay (NASDAQ: PICS), and it might be the most attractively valued high-growth fintech I have come across in a long time.
PicPay is often compared to Nu Holdings or StoneCo, but in my view it is a different animal. Where Nu is primarily a digital bank and Stone a payments processor, PicPay is evolving into something closer to a Brazilian super app – think WeChat Pay or Kaspi.kz. That combination of payments, banking, credit, insurance, investments, and even e-commerce inside a single interface is the business model I find most compelling globally. And here it trades at a fraction of the valuation its peers command.
Full disclosure: I am indirectly invested in PicPay through the Haas invest4 innovation fund (invest4.net), so conflicts of interest may exist. This is not investment advice or a recommendation.
What Does PicPay Actually Do – And How Does It Make Money?
PicPay started in 2012 as a QR-code-based mobile wallet – it was actually a pioneer of QR payments in Brazil well before the government launched the Pix instant payment system. Today, the platform has evolved into a comprehensive financial services ecosystem. On the consumer side, PicPay offers Pix payments, peer-to-peer transfers, bill payments, credit cards, personal loans, payroll-deducted loans, insurance distribution, and an investment platform. On the business side, it provides merchant acquiring via QR codes, POS solutions, prepayment of receivables, and working capital credit.
What makes PicPay’s model so attractive is the flywheel: users come for the free wallet and social payments, then get cross-sold into credit, insurance, and investments. The company reports that 32% of active users already use PicPay as their primary financial services platform. The revenue mix has shifted dramatically: in Q4 2023, 97% of revenue came from fees, commissions, and float. By Q4 2025, that had diversified to 48% fees/commissions/float, 19% secured credit, and 33% unsecured credit. This is a far more balanced and resilient revenue base.
PicPay also runs PicPay Shop (e-commerce and food delivery), PicPay Ads (in-app advertising), and recently launched “Epic” – a premium black card tier with telemedicine, toll payments, and Amazon Prime bundled in. The super app ambitions are real.
The Market: Large, Growing, and Structurally Favorable
Brazil’s digital financial services market is enormous. PicPay’s management estimates a total addressable market of roughly BRL 596 billion for consumer segments and BRL 129 billion for SMB segments. Real-time payments in Brazil are projected to grow at a 31% CAGR through 2027, and consumer credit penetration still has significant room to expand compared to developed markets.
Brazil has over 210 million people, a young and increasingly digital population, and a banking sector that has historically been dominated by a few large incumbents charging high fees. The opportunity for fintechs to capture share is structural, not cyclical. PicPay’s 42.7 million quarterly active clients represent perhaps 20% of the adult population – there is still enormous headroom.
One important macro consideration: Brazil’s 2026 presidential election (first round October 4) is shaping up to be highly competitive. Polls show President Lula and Senator Flávio Bolsonaro in a statistical dead heat for a potential second-round runoff. Lula’s approval has slipped to around 44% against 51% disapproval. A change in government toward more market-friendly policies could provide additional tailwinds for Brazilian equities broadly and fintechs specifically. But even under the current government, Brazil’s fintech sector has thrived thanks to the central bank’s progressive Open Finance framework and Pix infrastructure.
Also worth noting: Brazil is a major oil producer and biofuel grower, so higher global oil prices are relatively less damaging to its economy compared to other emerging markets. The macro backdrop is more resilient than many investors assume.
Culture and Management
This is where the story gets complicated – and where much of the discount comes from. PicPay is controlled by J&F International, which in turn is controlled by the Batista family. J&F is the holding company behind JBS (the world’s largest meat company), Banco Original, and several other businesses. The Batista brothers – Joesley and Wesley – were at the center of one of Brazil’s largest corruption scandals. In 2017, they admitted to illicit payments involving numerous politicians and signed a plea bargain. They were briefly imprisoned and forced out of day-to-day operations.
Since then, the family has undergone a significant governance overhaul. In 2023, insider trading accusations were dismissed by the CVM (Brazilian securities regulator). JBS successfully listed on the NYSE. And PicPay’s board now includes a majority of independent directors. The CEO, Eduardo Chedid Simões, is a professional manager (though José Antonio Batista Costa, a grandson of the patriarch, also serves on the board). J&F still holds approximately 88% of PicPay’s total voting power through super-voting Class B shares.
I view the Batista connection as a classic “why the opportunity exists” factor. Many institutional investors, especially ESG-conscious funds, will avoid anything linked to J&F. That depresses the valuation and creates the opportunity for less constrained investors. The operational execution, meanwhile, has been excellent – PicPay beat the top end of its IPO guidance across all key metrics in Q4 2025. Recent insider buying (a director purchased 100,000 shares at $11.80 in March 2026) also signals confidence.
Financials: Hyper-Growth with Improving Profitability
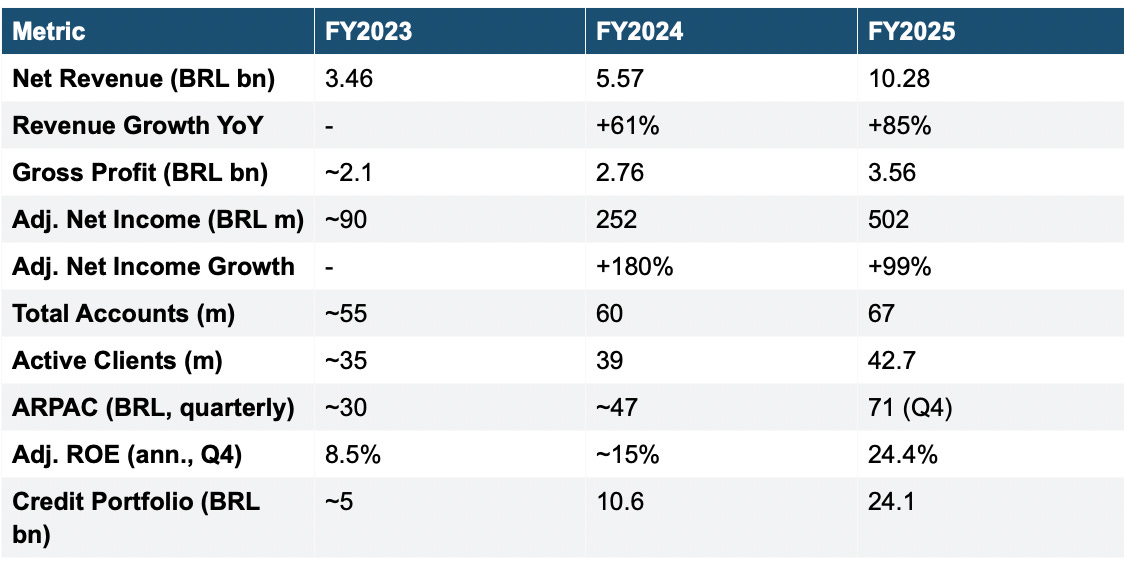
The numbers are remarkable. Revenue has tripled in two years from BRL 937 million in Q4 2023 to over BRL 3 billion in Q4 2025. More importantly, adjusted net income grew tenfold over the same period. The credit portfolio more than doubled in 2025 (+128% YoY) to BRL 24.1 billion, and the quarterly ARPAC (average revenue per active client) surged 52% to BRL 71. The company is growing both by adding new clients and by monetizing existing ones more intensively.
Q4 2025 adjusted earnings before taxes reached BRL 241 million, up 284% year-over-year. The annualized ROE expanded from 8.5% to 24.4% – approaching levels that would be considered excellent even for a mature bank. BofA expects ROE to eventually exceed 30%.
On the margin front, the gross profit margin sits at approximately 93% (reflecting the platform nature of the business), though the net income margin is still relatively thin at around 5% of total revenue due to heavy credit provisioning (BRL 2.53 billion in 2025). As credit quality stabilizes and the lending book seasons, net margins should expand meaningfully.
Valuation: Fair PE Model
Here is where PicPay really stands out. At the current price of approximately $14.30 per share, the market cap is around $1.85 billion. Let me walk through my Fair PE valuation framework.
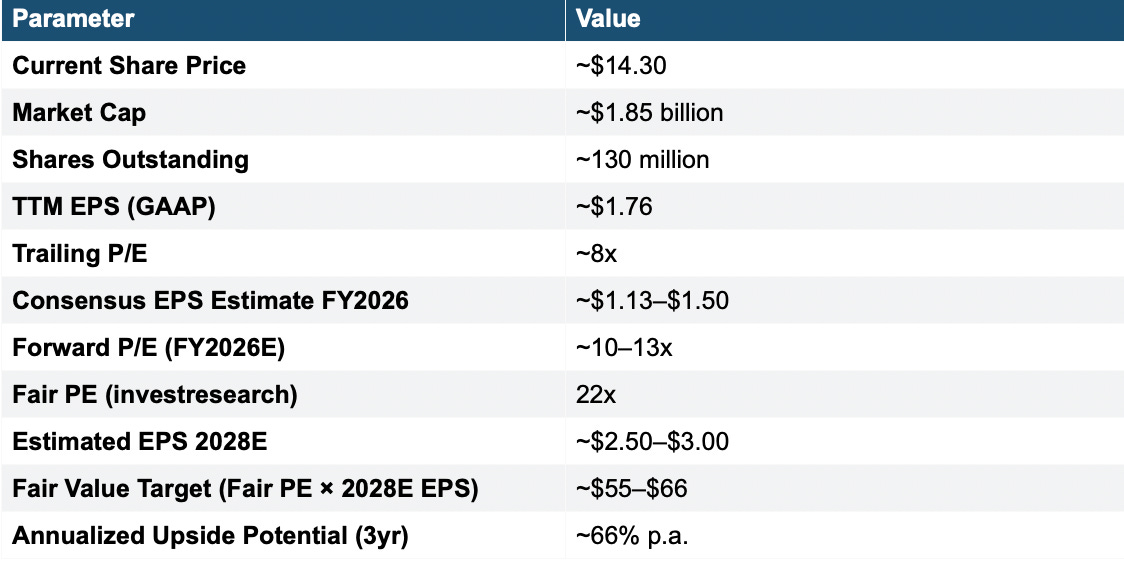
I assign a Fair PE of 22x to PicPay. This is a company with 40%+ revenue growth, rapidly expanding profitability, a non-cyclical digital financial services model, and strong operating leverage. For comparison, Nu Holdings trades at roughly 25–30x forward earnings, and Inter&Co at around 15–18x. A Fair PE of 22x is conservative for a business of this quality and growth trajectory.
Even if I use a more conservative 30% earnings CAGR (below the company’s current pace) and project forward to 2028, applying 22x to estimated EPS of $2.50–$3.00 yields a target price range of $55–$66. From the current price of ~$14.30, that implies an annualized return potential of approximately 66% per year over the next three years. This is among the highest return potentials I currently see in my investable universe.
Analyst consensus backs up the bullish case: the average 12-month price target is around $23 (with Mizuho at $23 and BofA at $27), implying over 60–90% upside from current levels even on a shorter time horizon. Citi estimates PicPay trades at approximately 9x 2027E earnings.
Why Does This Opportunity Exist?
When a stock is this cheap relative to its growth, there’s always a reason. For PicPay, I see several factors creating the discount:
Batista/J&F overhang: The controlling family’s corruption history makes many institutional investors uncomfortable. ESG screens and reputational concerns keep capital away. J&F holds 88% of voting power through dual-class shares, limiting minority shareholder influence.
Fresh IPO with limited track record: PicPay only went public in January 2026 at $19/share. The stock dropped significantly post-IPO (hitting a low of ~$9.88), which is common for newly listed companies as lockup-constrained insiders or IPO participants sell. The float is small (~22 million shares), which amplifies volatility.
Brazil discount: Brazilian equities broadly trade at low multiples due to high interest rates (Selic), currency volatility, and political uncertainty. The current election cycle adds to the uncertainty.
Credit risk perception: PicPay’s rapid credit expansion (portfolio up 128% YoY) raises legitimate concerns about asset quality. A one-time ECL methodology change in Q4 temporarily lifted Stage 3 NPL formation to 7.1% (expected to normalize to ~3.7–4.0%). Investors burned by StoneCo’s credit losses in 2022 are cautious.
I believe all of these factors are already priced in at current levels, and most are improving directionally.
Risks
Credit quality deterioration: This is the single biggest risk. Credit loss allowance expenses surged 185% to BRL 2.53 billion in 2025 as the loan book expanded rapidly. If Brazil enters a recession or credit algorithms underperform, losses could spike. Management is still in the process of internalizing (building in-house) some of its credit scoring models, and any misstep could be costly. StoneCo’s painful experience with credit in 2022 is a cautionary precedent.
Cash burn and capital needs: Operating cash flow swung to a BRL 3.74 billion outflow in 2025 as the lending business consumed capital. Cash declined from BRL 7.5 billion to BRL 3.9 billion. The company expects capital ratios to trend toward targets of 11–11.5% CET1, but if growth continues at this pace, additional capital raises (dilutive equity or expensive debt) may be necessary before internal capital generation catches up (expected around 2027).
Controlling shareholder risk: The Batista family controls 88% of voting rights. While governance has improved, dual-class structures inherently limit minority shareholder protections. Related-party transactions or strategic decisions that favor the controlling family over public shareholders remain a tail risk.
Competitive pressure: PicPay competes with Nubank (which has far more resources and a much larger user base), Mercado Pago, Inter&Co, PagBank/PagSeguro, and Brazil’s traditional banks. Customer acquisition costs could rise, and the race to offer the best rates on credit and savings products could compress margins.
Currency risk: PicPay earns in BRL but is listed in USD. A depreciating real would reduce dollar-denominated earnings even if BRL results remain strong. The BRL has been volatile, driven by fiscal policy concerns and global risk appetite.
Regulatory risk: Brazil’s central bank has been progressive, but regulations around consumer lending rates, Open Finance data sharing, or payment fees could change, particularly under a populist government.
Conclusion
PicPay is a rare combination of high growth, improving profitability, and genuinely cheap valuation. A company that is growing revenue at 85%, doubling its earnings annually, expanding ROE toward 25%, and building a true super app platform in the world’s fifth-largest country – all while trading at roughly 8–10x trailing earnings – deserves attention.
The risks are real: credit quality in a rapidly scaling loan book, the Batista family overhang, and the typical volatility of Brazilian equities. This is not a stock to go all-in on. But as a fundamental position in a diversified portfolio of high-quality growth companies at fair valuations, PicPay offers one of the most compelling risk/reward profiles I have found recently.
With a Fair PE of 22x and my three-year return target of approximately 66% per annum, PicPay is one of the highest-conviction ideas in my current opportunity set. The key catalysts to watch are Q1 2026 earnings (guided for ~BRL 140 million GAAP net income), continued credit quality normalization, the Brazilian election outcome, and whether institutional investors begin to look past the J&F stigma as the public track record lengthens.
The beauty of this investment case is the triple growth engine: PicPay is still growing its customer base, it is increasing revenue per customer through cross-selling (ARPAC +52%), and it is benefiting from massive operating leverage as fixed costs get spread across a larger base. This is the same playbook that made Kaspi.kz and Nu Holdings multi-baggers, and PicPay is at a much earlier stage of the curve.
As always, do your own research and form your own opinion.
────────────────────────────────────────────────────────────
Risk Disclaimer
This article reflects the personal opinion of Philipp Haas and is for informational and educational purposes only. It does not constitute investment advice, financial advice, or a recommendation to buy or sell any securities. Investing in stocks involves risk, including the possible loss of principal. Past performance is not indicative of future results. The author is indirectly invested in PicPay (PICS) through the Haas invest4 innovation fund, which may create conflicts of interest. Always conduct your own due diligence before making investment decisions.
PicPay (PICS) is part of the portfolio of the cost-efficient Haas invest4 innovation fund (invest4.net), which focuses on attractively valued growth companies and offers a tax- and cost-efficient way to invest in this type of opportunity.