

Introduction: Why I Am Looking at Pagaya Right Now
There are stocks that make your pulse race a little faster. Pagaya Technologies (NASDAQ: PGY) is one of them. This is a high-beta stock — probably among the highest-beta names in my entire investment universe. When things go right, it could be tremendously rewarding. When they go wrong, the volatility can be brutal. At around $11 per share and a market capitalization of roughly $900 million, I believe Pagaya has never been this cheap relative to its earnings power. The stock traded at $290 during the 2021 bubble. Today it trades at a single-digit P/E ratio, even though this is fundamentally a growth company.
Full disclosure: I am indirectly invested in Pagaya through the Haas Invest4 Innovation Fund. This may create conflicts of interest, and nothing in this article constitutes investment advice or a recommendation.
So let me walk you through why I find this name so compelling — and why it has fallen so hard.
Product & Business Model: What Does Pagaya Actually Do?
Pagaya is an AI-powered lending network. But unlike Upstart or LendingClub, Pagaya does not build a consumer-facing brand. It does not try to attract borrowers directly. Instead, Pagaya operates as the invisible infrastructure layer behind banks, fintechs, and financial institutions.
Here is how it works: Imagine a customer walks into a bank and applies for a personal loan. The bank runs its own credit algorithm and decides to decline the application — not because the customer is necessarily a bad risk, but because the customer does not fit the bank’s specific lending criteria. Traditionally, that would be the end of the story. The customer leaves, the bank loses a potential client, and everyone is worse off.
Pagaya changes this dynamic. The bank can feed that declined application into the Pagaya network. Other banks and financial partners connected to the network can then evaluate the application using Pagaya’s AI credit algorithm and decide whether they want to extend credit. If a match is found, the original bank earns a referral fee, Pagaya earns a network fee, and the lending partner acquires a new customer. Everyone wins.
If you are German and want a comparison: think of Hypoport, which was one of the best-performing German stocks for many years and multiplied 50x. Hypoport built a similar platform concept for mortgage distribution in Germany. Pagaya is doing something analogous but for the much larger U.S. consumer credit and auto loan market, powered by artificial intelligence.
Key Products
Pagaya offers several products to its partners. The flagship is Decline Monetization, which routes rejected loan applications to the network. There is also Dual Look, which evaluates applications concurrently with the bank in real time, and First Look, which routes certain segments directly to the network. On the marketing side, Pagaya provides an Affiliate Optimizer Engine for customer acquisition through third-party channels, a Direct Marketing Engine to help partners target new customers, and FastPass to accelerate the lending process.
On the capital markets side, Pagaya does not hold these loans on its own balance sheet — or only to a very small extent. Instead, it bundles the originated loans into asset-backed securities (ABS) and sells them to institutional investors. The company has raised over $27 billion through its ABS program since inception across more than 85 transactions, making it one of the leading personal loan ABS issuers in the United States.
Why the Model Makes Sense
What I particularly like about Pagaya’s business model is the platform economics. Unlike B2C lenders that have to spend heavily on customer acquisition, Pagaya sits behind its partners. The customer acquisition cost is borne by the partner bank or fintech, not by Pagaya. Pagaya provides the AI infrastructure, the credit algorithm, and the capital markets connectivity. This is inherently more capital-efficient and scalable.
The AI credit algorithm is the core moat. Credit scoring and loan approval is one of the earliest and most natural use cases for artificial intelligence. It is fundamentally an optimization problem: given a set of data points about a borrower, can you predict repayment probability better than traditional FICO-based models? Pagaya claims its models incorporate far more variables — income stability, cash flow patterns, payment histories, and more — to make real-time credit decisions. The more data flows through the network, the better the algorithm gets. This creates a data flywheel that is very hard for competitors to replicate.
As of the latest reporting, Pagaya works with over 30 lending partners, including heavyweights like SoFi, Klarna, Ally Financial, and Westlake Financial. The company is also in discussions with many of the top 25 U.S. banks. With roughly 42% of U.S. consumers underserved by traditional credit scoring, the total addressable market is enormous.
Market: Size, Growth, and Cyclicality
The U.S. consumer lending market is massive. Personal loans, auto loans, point-of-sale financing, and credit cards together represent a multi-trillion-dollar addressable market. Pagaya started with personal loans but has been expanding into auto loans (a bigger and arguably better product with lower default rates) and point-of-sale financing for home improvements, medical procedures, and other large purchases.
The market is undeniably cyclical. Pagaya’s business is tied to interest rates, default rates, and overall consumer credit health. When rates are high and recession fears dominate, sentiment turns against anything connected to consumer credit — which is precisely what has happened to PGY’s stock price. But cyclicality works both ways. If and when the macro environment normalizes, the earnings leverage for a platform like Pagaya is significant.
Regulatory risk is real. There has been some discussion around potential maximum interest rate caps, which could impact parts of the lending market. In China, we have seen how quickly regulation can disrupt lending platforms. In the U.S., the regulatory environment is generally more stable, but it is worth monitoring, especially under the current political administration. That said, Pagaya’s model as an infrastructure provider rather than a direct lender somewhat insulates it from the harshest regulatory scenarios.
Culture & Management: Founder-Led with a Long-Term Vision
Pagaya was co-founded in 2016 by Gal Krubiner (CEO), Yahav Yulzari, Avital Pardo, and Sanjiv Das. Krubiner remains CEO and has been the driving force behind the company’s growth and strategic direction. The team has Israeli tech DNA combined with deep Wall Street experience — Sanjiv Das, who serves as President, previously led CitiMortgage and brings decades of institutional credibility.
I like that management has been very disciplined about pivoting toward profitability. After years of investing in growth and absorbing meaningful losses from legacy loan vintages (particularly 2021–2023 vintages that were originated in a challenging funding environment), management has decisively shifted toward credit discipline. In late Q4 2025, they proactively cut exposure to higher-risk credit tiers even though it hurt short-term volume growth. This tells me they are thinking long-term, which is exactly what I want to see.
The company has around 518 employees as of early 2026, which is lean for a business generating $1.3 billion in revenue. This speaks to the scalability of the AI-driven platform model.
Financials: The Numbers Tell a Compelling Story
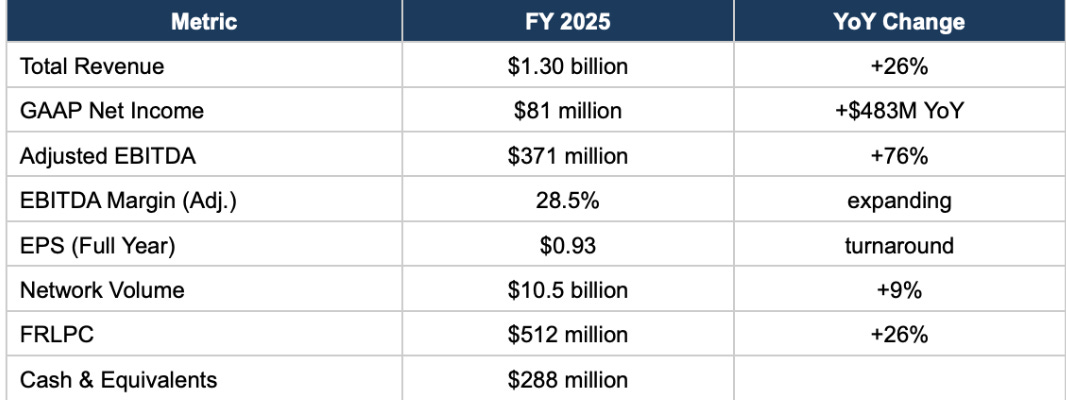
Full-Year 2025 Results
Q4 2025 Highlights
Q4 2025 was a strong quarter in terms of profitability: $34 million in GAAP net income (a record), $98 million in adjusted EBITDA representing a 29% margin, and $80 million in operating cash flow. Revenue came in at $335 million, up 20% year-over-year. The EPS of $0.80 significantly beat analyst estimates of $0.69. However, revenue slightly missed expectations of $349 million, and network volume growth decelerated to just 3% year-over-year as management deliberately pulled back from higher-risk credit segments.
This deliberate trade-off of short-term volume for long-term quality is exactly the kind of decision I want to see management make — even if the market initially punished the stock for it, sending it down 25% after the earnings release.
2026 Guidance
For 2026, Pagaya has guided for total revenue of $1.4 billion to $1.575 billion and GAAP net income of $100 million to $150 million. This guidance reflects continued conservatism, with management prioritizing credit quality over aggressive growth. They have indicated that the production cuts made in late Q4 2025 will persist, reducing monthly volume by roughly $100–$150 million. If the macro environment stabilizes, there could be meaningful upside to these numbers.
Margins and Profitability
The margin improvement story is remarkable. Adjusted EBITDA margins expanded from roughly 7% to 20% over just four quarters in 2024, and then continued to improve to 28.5% for FY2025. In Q4 2025, the margin was 29%. The GAAP net income margin reached roughly 6% for the full year 2025, with Q4 at approximately 10%. For a company that was deeply unprofitable just a year earlier (FY2024 had a net loss of over $400 million, largely due to impairments on legacy loan vintages), this turnaround is extraordinary.
Adjusted net income for 2025 was $275 million, which excludes non-cash items like share-based compensation. The return on equity is improving rapidly as the company moves from massive losses to consistent profitability.
Funding Structure: The Blue Owl Question
One reason the stock is so depressed is concern about Pagaya’s funding structure. Pagaya does not hold most of these loans itself. Instead, institutional investors purchase the loans, either through ABS transactions or through forward flow agreements. Blue Owl Capital, a major alternative asset manager with over $280 billion in AUM, committed to purchasing up to $2.4 billion in consumer loans through Pagaya’s network over a 24-month period in early 2025. Castlelake agreed to purchase up to $2.5 billion in consumer loans. And most recently, Sound Point Capital committed up to $720 million specifically for point-of-sale loans.
Blue Owl has been in negative headlines related to its broader private credit business, and some investors worry about contagion effects on Pagaya. However, the Blue Owl fund investing in Pagaya’s loans is a separate vehicle from the segments facing challenges. Unless we see a systemic 2008-style credit crisis, I believe this concern is overblown. And even then, Pagaya could replace funding partners — it is the platform, not the capital provider.
In 2025, Pagaya raised $8.5 billion in ABS across all three of its AAA-rated shelves. In early 2026, the company already launched new transactions including a $400 million auto ABS and an $800 million personal loan ABS, demonstrating continued strong institutional appetite for Pagaya-originated assets.
Valuation: The Fair PE Model
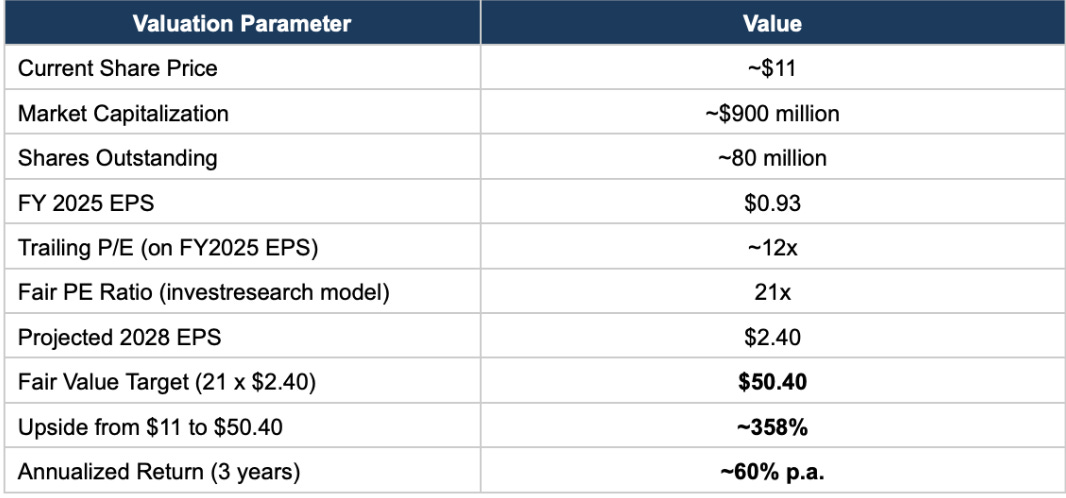
Using the investresearch Fair PE model, I assign a fair P/E ratio of 21 to Pagaya. This is quite conservative for a company with double-digit organic revenue growth and even faster earnings growth. Remember, this stock traded at 10x revenue during the 2021 hype. A P/E of 21 for a profitable, growing AI platform business is far from aggressive.
With projected 2028 EPS of $2.40 — which aligns with analyst consensus forecasting roughly $240 million in net income by 2028 — the fair value target is $50.40 per share. From a current price of approximately $11, that represents roughly 358% upside over three years, or approximately 60% annualized returns.
Even if we use the more conservative 2026 guidance midpoint of $125 million in GAAP net income (roughly $1.55 EPS), the stock at $11 trades at just 7x forward earnings. For context, the average Wall Street analyst price target is around $28–$34, implying 150–200% upside from current levels.
Why Does This Opportunity Exist?
If the valuation is so compelling, why is the stock so cheap? There are several reasons, and understanding them is crucial:
Recession and credit cycle fears: The market is pricing in a potential credit deterioration. Higher interest rates, persistent inflation, and political uncertainty (tariff threats, regulatory rhetoric) all weigh on sentiment for anything connected to consumer lending.
Blue Owl headlines: The negative press around Blue Owl’s broader private credit business has spooked investors, even though the specific fund investing through Pagaya’s platform is a separate vehicle.
Legacy impairments: Pagaya’s 2021–2023 loan vintages resulted in significant write-downs in 2024 ($400+ million in net losses). While management says these vintages are largely behind them, the memory lingers.
Software sector sell-off: Pagaya gets classified alongside software and fintech companies, many of which have been aggressively sold off. The stock got caught in broader sector rotation despite being a genuine AI beneficiary with real profitability.
Revenue miss in Q4: Even though Q4 EPS massively beat expectations, the slight revenue miss and deceleration in network volume growth triggered a 25%+ sell-off. The market punished discipline over growth.
High beta and small cap: With a beta of about 4.4 and a market cap under $1 billion, institutional investors often cannot or will not hold the stock. This creates structural undervaluation.
Risks: What Could Go Wrong
Deep recession scenario: If the U.S. enters a severe recession with sharply rising unemployment and default rates, Pagaya’s network volume would decline, funding partners could pull back, and the company could face fresh impairments on retained loan positions. A 2008-style event would be devastating.
Regulatory intervention: Interest rate caps, changes to consumer lending regulations, or enhanced scrutiny of AI-driven lending could fundamentally alter the business model.
Funding dependency: If institutional investors lose appetite for consumer loan ABS or if major partners like Blue Owl, Castlelake, or Sound Point pull back, Pagaya would struggle to maintain its network volume.
Competition: Upstart, traditional credit bureaus, and large banks developing in-house AI credit models could erode Pagaya’s competitive advantage. The moat is strong but not unassailable.
Dilution: Pagaya’s share-based compensation has been substantial. While the company generated $275 million in adjusted net income in 2025, GAAP net income was $81 million, reflecting the dilution impact of SBC.
Concentration risk: A significant portion of network volume flows through a small number of large partners. If a major partner like SoFi were to build or switch to an in-house solution, it would materially impact Pagaya.
Conclusion: A Calculated High-Beta Bet
Pagaya Technologies is not a stock for the faint of heart. The volatility is real, the risks are material, and the macro environment remains uncertain. But at $11 per share and a trailing P/E of roughly 12x — for a company growing revenue at 20%+ and earnings at 50%+ with a genuine AI competitive moat, an expanding partner network, and a clear path to $100–$150 million in annual GAAP net income — I believe the risk/reward is exceptionally attractive.
The investresearch Fair PE model suggests a fair value of $50.40 based on a Fair PE of 21 applied to projected 2028 EPS of $2.40, implying approximately 60% annualized returns over the next three years.
I believe this is a stock where you can manage the risk through position sizing. You do not need to make it a 10% position. But having some exposure to a company with this earnings trajectory at this valuation, with the wind of AI and expanding financial infrastructure at its back, strikes me as a sensible decision.
The chart shows some stabilization around the $11 level after the post-earnings sell-off, and I think based on my model, one can initiate a first position here. If the macro fears turn out to be overblown, this could be one of the biggest winners in my portfolio over the coming years. If everything goes perfectly — new bank partners, auto loans scaling, interest rates normalizing — this could even have ten-bagger potential on a multi-year horizon from current levels.
But as always: do your own research. This is not financial advice or a recommendation.
RISK DISCLAIMER
This article is for informational and educational purposes only and does not constitute investment advice, a recommendation, or a solicitation to buy or sell any securities. Investing in stocks, particularly high-beta small-cap stocks like Pagaya Technologies (PGY), involves significant risks including the potential loss of your entire investment. Past performance is not indicative of future results. The author may hold positions in the securities discussed and may trade them at any time without notice. Always conduct your own due diligence and consult with a qualified financial advisor before making any investment decisions.
Pagaya Technologies (PGY) is part of the portfolio of the cost-efficient Haas Invest4 Innovation investment fund (invest4.net). This may constitute a conflict of interest. Fund holdings can change at any time.
© 2026 Philipp Haas | investresearch.net |