

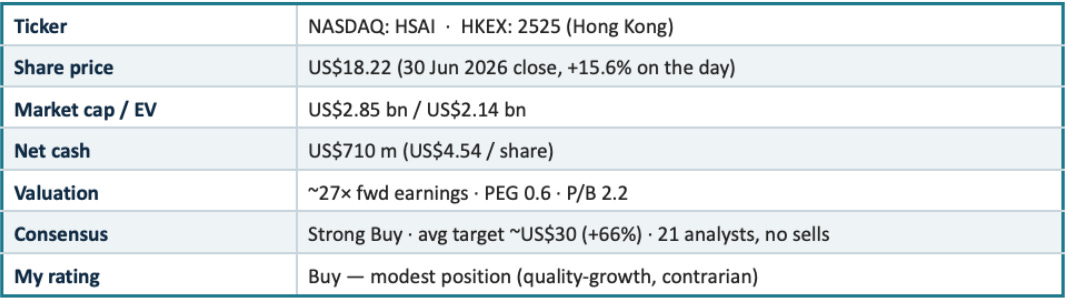
Every so often I come across a business that sits exactly where I like to invest: a profitable, fast-growing world leader, operating in an obvious future market, that the market has quietly fallen out of love with. Hesai Group is that stock for me today. I want to walk you through why I bought it — in Hong Kong, for the Haas Invest4 Innovation fund — and why I think it is one of the more asymmetric ideas in my coverage universe right now.
The narrative is simple. After AI on our laptops, I believe robotics — physical AI — is the next truly enormous business opportunity. A robot that actually works, that can do the jobs in factories, warehouses, care homes and eventually our living rooms that people would rather not do, is a bigger prize than any chatbot. And every one of those robots, along with every self-driving car, needs to see. For years, LiDAR — the laser-based 3D sensing that gives machines depth perception — was simply too expensive. That has changed. It is now in mass-market robot lawnmowers costing a few hundred euros, in a fast-growing share of new Chinese cars, and it is heading into humanoids. Hesai is the global number one supplier of it.
Here is the investment case in one breath: Hesai is the world’s largest LiDAR maker, roughly 40% of the global market and over half of China’s long-range automotive segment, growing revenue ~44% this year and ~41% next, already profitable, sitting on net cash of about US$710 million, an Nvidia autonomous-driving partner — and yet it trades at roughly 20× forward earnings with a PEG around 0.6, near its 52-week low. On my Faires-KGV (fair P/E) framework I arrive at a fair multiple of 27, and because earnings are compounding at ~40% a year at that same fair multiple, I see a base case pointing to roughly 50% annualised upside over the next three years. Add the optionality of the robotics and actuator business the company is now building, and the risk/reward is compelling. It is China, so I size it as a modest position — but it is a position.
1. Product, business model, brand & moat
What the company actually does
Hesai designs and manufactures LiDAR — light detection and ranging sensors that fire laser pulses and measure their return to build a precise, real-time 3D point cloud of the world. Founded in 2014 in Shanghai, the company started in laser-based gas sensing and pivoted to LiDAR in 2016. Today its sensors go into three broad buckets: ADAS-equipped passenger cars (the big volume driver), autonomous mobility (robotaxis and robotrucks), and robotics (delivery robots, cleaning robots, AGVs, and increasingly humanoids).
How they make money
The core model is hardware at scale: Hesai sells LiDAR units to automakers and robotics OEMs, and the economics improve as volumes ramp and its in-house chips drive cost down. This is the important shift — Hesai has moved from an expensive, hand-assembled product to a chip-based one. It is the only LiDAR company in the world to develop all seven core components in-house: the laser transmitter, receiver, driver, TIA, ADC, digital signal processor and controller. Twenty-one of its in-house designs have passed automotive-grade AEC-Q certification, cumulative shipments have passed 230 million units and should top 300 million by the end of 2026. On top of the hardware, management is now layering a second, higher-margin, recurring-revenue model around spatial data and software (more on that later).
Brand & moat
The brand, within its industry, is dominant. Hesai has been ranked the world’s number-one long-range ADAS LiDAR supplier by shipments for five consecutive years, and it has won mass-production design slots on more than 160 vehicle models across 40 automotive brands — including every one of China’s top-ten automakers. That installed base is the moat. Automotive design wins are multi-year and sticky; a carmaker that has validated Hesai across a model line does not casually re-qualify a rival mid-cycle.
The deeper moat is vertical integration. Because Hesai owns its full ASIC stack, it controls performance, cost and supply in a way peers relying on merchant chips cannot. That is what lets it run the dual roadmap it talks about — “ultimate performance” (the ETX flagship) and “ultimate value” (the ATX for the mass market) — and still make money. Its flagship Picasso chip is the world’s first 6D full-color, ultra-sensitive LiDAR SPAD-SoC: it fuses RGB colour with XYZ depth at the chip level, producing colourised point clouds. In plain terms, it lets a LiDAR start to do the job of a camera — but without a camera’s weaknesses in glare, darkness or bad weather. That is a genuinely differentiated capability, and it is the kind of thing that keeps a moat widening rather than eroding.
2. The market: how big, how fast, how political
The automotive LiDAR market crossed US$1 billion for the first time in 2025, up around 60% year-on-year, with roughly 3.1 million primary ADAS units shipped. And this is still the early innings. The regulatory and safety shift toward L3 autonomy is the real prize: cars moving to L3 need redundancy, which means multiple LiDAR per vehicle. Hesai’s own framing is three to six LiDAR per L3 car, worth roughly US$500–1,000 of content per vehicle. That is a step-change in addressable market from today’s single-sensor ADAS cars.
Within that market Hesai is the clear leader. Depending on the measure, it holds roughly 37–43% of the global LiDAR market and is number one by shipment volume. In China’s long-range automotive segment — the highest-value slice — Gasgoo put Hesai at 51% share in February 2026, rising to 55% in March, more than double the number-two player, and number one for fourteen consecutive months. In robotaxi LiDAR it has historically held the majority of the market.
Now the political dimension, because it cuts both ways and it is the crux of the opportunity. Chinese LiDAR companies collectively account for around 92–95% of the global market. This is one of those strategically important technologies that has ended up almost entirely in Chinese hands — which is a structural tailwind for Hesai’s volumes and pricing power, but also the reason the stock carries a geopolitical discount. LiDAR is cyclical in the sense that it rides the auto production and capex cycle, but the secular adoption curve (penetration of LiDAR into new models) is steep enough that unit growth has so far swamped any cyclicality. I treat the China/US listing risk as the main political overhang, not demand.
3. Culture & management
Hesai is founder-led, which is exactly what I look for. Co-founder and CEO Dr. Yifan “David” Li has run the company since 2014 and still frames it as a deep-tech business “scaling from 1 to 10.” Insiders own around 17.5% of the shares, so management’s interests are aligned with mine as an outside shareholder.
What impresses me is the long-termism of the strategy relative to a hardware company’s usual horizon. Rather than milking the automotive LiDAR win, management has explicitly identified robotics and physical AI as the next decade’s growth engine and is investing ahead of it — launching Strategic Growth Initiatives it describes as the “eyes and muscles” of physical AI. That is a bold, forward-leaning bet from a team that could have simply harvested its lead. Combined with an A-grade result on a VDA 6.3 process audit and in-house factories in both China and Thailand (the Thai base also helps navigate tariffs), this reads to me as a disciplined, engineering-driven culture rather than a hype machine.
4. Financials & recent developments
This is where Hesai separates itself from the long, sad history of LiDAR SPACs that never made a cent. 2025 was the inflection: revenue of RMB 3.03 billion (+46%) and the company’s first full year of GAAP profitability, with net income of RMB 436 million. On a trailing-twelve-month basis through Q1 2026, revenue is RMB 3.18 billion (+42%).
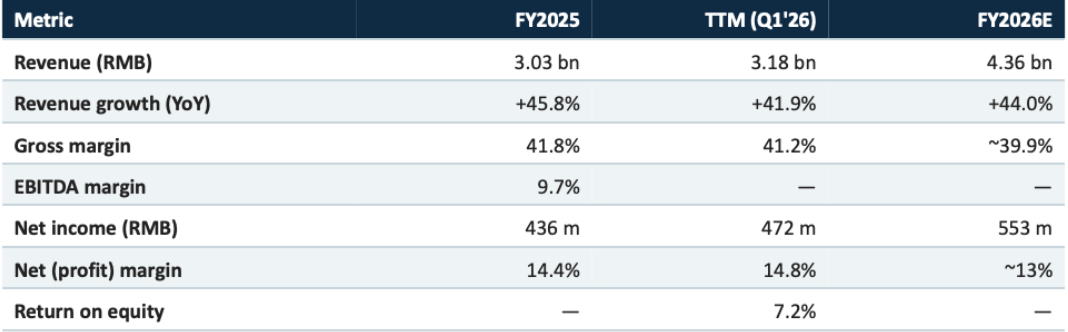
On margins, I want to be precise, because the headline net margin flatters the picture. Gross margin is healthy at roughly 41–42%. But the operating margin is still thin at around 6% — the business only recently crossed into operating profit. The reported net margin of ~14% is meaningfully higher than the operating margin because a big chunk of profit comes from interest income on that ~US$710 million net-cash pile plus other non-operating items. EBITDA margin was ~9.7% in 2025. Return on equity is a modest ~7%, held down both by the thin operating margin and by the large, low-returning cash balance sitting on the balance sheet. I flag this deliberately: the bull case is not that Hesai is already a high-return compounder — it is that operating leverage on 40%+ growth turns a 6% operating margin into something much better, at which point ROE re-rates too.
The forward trajectory is what matters. Consensus has revenue reaching RMB 4.36 billion in 2026 (+44%) and RMB 6.13 billion in 2027 (+41%), with operating income swinging decisively positive and EPS growth of roughly 67% into 2027. Analysts model ~38% revenue and ~35% EPS growth over the next three years. This is a genuine high-growth, now-profitable business — not a story stock.
5. Valuation — my Faires-KGV (fair P/E) model
My approach is always the same: I build a fair P/E from the ground up rather than anchoring on where the stock has traded. I start from a base multiple for a quality growth compounder and adjust for growth, moat and risk.
My fair P/E for Hesai is 27. Here is the elegant part, and the reason I find this so attractive: the stock already trades at roughly 27× forward earnings. In other words, I am being asked to pay fair value — and no more — for a business compounding earnings at ~40% a year. When you buy a company at its fair multiple and that multiple holds while earnings grow ~40%+ annually, your return tracks the earnings growth. That is the mechanical basis for my expectation of roughly 50% annualised upside over the next three years: ~40–45% from earnings compounding, plus the normalisation of a currently sentiment-depressed multiple back toward fair, plus the free option on robotics and Kosmo that consensus barely captures.
Sanity checks support it rather than contradict it. The sell-side consensus target sits around US$30 — about 66% above the current price — with a Strong Buy rating from 21 analysts and not a single sell. The PEG is roughly 0.6. And the enterprise value is only ~US$2.1 billion once you strip out the net cash. For a global number-one in a structural growth market, that is cheap. The obvious pushback — “27× is not optically cheap” — misses that the multiple is fair for the growth, and that the earnings denominator is growing fast enough to do the heavy lifting.
6. Risks — and why the opportunity exists
A stock this good does not sit near its 52-week low by accident, so let me be honest about why. The shares are down roughly 17% over the past year and, even after a sharp bounce, trade below both their 50- and 200-day moving averages. Three things explain it:
China sentiment. This is the big one. Chinese ADRs have been out of favour, and Hesai’s price action this year has been driven far more by top-down China risk-off than by anything in its own numbers. That sentiment can — and I think will — turn, and it tends to turn on sentiment, not fundamentals, which means the re-rating can be fast when it comes.
Margin-mix worries. After Q1, the shares actually fell double digits because the growth is being led by cheaper, lower-margin mass-market units (the ATX), which weighs on blended gross margin even as volumes explode. The market is nervous that Hesai is buying share with price. I read it as deliberate land-grab economics: win the model slots now, harvest margin as the in-house chips scale.
Structural China/ADR risk. Delisting risk, VIE/ADR structure and the ever-present possibility of policy or export-control friction are real and cannot be waved away. Huawei is also a serious, well-resourced competitor with its own in-house LiDAR and intelligent-driving ecosystem, holding roughly a quarter of the automotive market — and RoboSense, a separately Hong-Kong-listed rival (not, as is sometimes muddled, a Huawei subsidiary), leads on some passenger-car unit-share measures. Competition is real.
This is precisely why the opportunity exists. The business is executing — record shipments, first-year profits, share gains, an Nvidia partnership — while the share price is being set by macro fear and a margin-optics debate. That gap between operating reality and market perception is what I am buying. It is also why I keep the position modest: the fundamental case is strong, but the risks are genuine and largely outside the company’s control.
7. Latest news & earnings
Q1 2026 (reported 19 May): revenue of RMB 680.6 million (US$98.7 million), up 30% year-on-year and an eighth consecutive quarter of growth; LiDAR shipments of 471,723 units, more than double a year earlier; GAAP net income of RMB 18.3 million; gross margin above 39%. Critically, management guided 2026 LiDAR shipments to roughly double, to 3.0–3.5 million units, and reaffirmed the strategic pivot from “spatial perception” to “spatial intelligence.”
The product and partnership news flow has been dense. In January, Hesai was selected for Nvidia’s DRIVE Hyperion 10 platform, supplying its ETX LiDAR for L3/L4 architectures — a major external validation. It announced a Mercedes-Benz partnership for autonomous-driving models. At its April Tech Day it unveiled the Picasso 6D full-colour chip and the upgraded 4,320-channel ETX (mass production in H2 2026), plus Kosmo, a spatial-intelligence device built on its LiDAR plus proprietary 3D reconstruction and generative algorithms. Management explicitly frames Kosmo as the entry point to a recurring-revenue model addressing robotics simulation, immersive media and beyond — a business it sizes in the trillions of RMB. On the robotics side it has piled up design wins: an exclusive slot with KargoBot, 200,000 units to Zelos, largest-supplier status with Neolix, an entry into e-two-wheelers with NIU, and its JT128 sensor powered Honor’s humanoid “Lightning” to a world-record run at the first humanoid half-marathon. It is the only LiDAR company on Morgan Stanley’s “Humanoid Tech 25” list.
Two housekeeping items worth knowing: shareholders approved an 8-for-1 stock split effective 10 July 2026 at the 26 June AGM (cosmetic, but it lowers the per-share price and can broaden the shareholder base), and the shares jumped ~16% on 30 June as the robotics narrative and split drew fresh attention. The next earnings report is due 13 August 2026.
8. Conclusion & investment case
Hesai lets me own two megatrends — autonomous driving and physical-AI robotics — through a single, profitable, cash-rich market leader, at a fair multiple on rapidly growing earnings. That is a rare combination, and it is why the stock is in the Haas Invest4 Innovation fund.
I see three distinct catalysts that can drive a re-rating from here:
The autonomous-driving ramp. The shift to L3 multiplies LiDAR content per car from one sensor to three-to-six, at US$500–1,000 per vehicle. As Hesai’s design-win backlog (over 160 models) converts to volume and shipments double in 2026, revenue and — crucially — operating leverage should follow.
Robotics as a second S-curve. Hesai is already number one across multiple robotics-LiDAR segments. Robotrucks, robotaxis, warehousing, service robots and humanoids are all future demand pools it can address with its existing sensing core.
Actuators and Kosmo — the optionality. Moving from the “eyes” of robots into their “muscles” — robotic actuation modules — plus a recurring-revenue spatial-data platform in Kosmo, opens markets far larger than sensors alone. It is further from the core and unproven, so I don’t pay for it — but it is a free call option embedded in the price.
Put it together: a world-leading, founder-led, profitable compounder growing ~40% a year, on a fair P/E of 27 that I expect to deliver on the order of 50% annualised upside over three years, with genuine robotics optionality on top. The offsetting China and margin-mix risks are real, which is why this is a conviction idea sized as a modest position rather than a large one — but for me the asymmetry is clearly on the upside. I own it, and I’m comfortable owning it.
Risk disclaimer & conflict of interest
Please note: I, Philipp Haas, hold Hesai Group shares (Hong Kong line, HKEX: 2525) within the Haas Invest4 Innovation fund (invest4.net), a cost-efficient innovation fund I manage. This creates a conflict of interest, as I may benefit from a rising share price.
This article reflects my personal opinion and is intended for information and educational purposes only. It is expressly not investment advice, a recommendation, or a solicitation to buy or sell any security. Investments in equities — and in Chinese ADRs / small-caps in particular — carry substantial risk, including the total loss of capital. Share prices, financial figures and market-share data are as of 30 June / 1 July 2026 and can change quickly. Figures were verified against current public sources at the time of writing; forward estimates are consensus figures and are inherently uncertain. Please do your own research and, where appropriate, consult a licensed advisor before investing. Past performance is not indicative of future results.