

ntroduction: The $23 Billion Italian Company Hiding in Plain Sight
Let me present to you what is arguably the most successful — or at least most valuable — European internet company after Spotify. And I would bet that most of you have never heard of it, even though more than half a billion people use its products every month.
The company is Bending Spoons, an Italian technology group from Milan that went public on the Nasdaq on July 1, 2026 under the ticker BSP. The IPO was priced at $29 per share, above the marketed range of $26–28, raising $1.68 billion. On the first trading day, the stock popped almost 40% to close at $40.50 — briefly valuing the company at roughly $25.7 billion. It has since pulled back to around $36, which still puts the market capitalization at approximately $22.7 billion. For context: in its last private funding round in October 2025, Bending Spoons was valued at just $11 billion. The public market more than doubled that in a single day.
Ironically, this is not a shiny high-tech innovator. Bending Spoons does what Europeans, in my view, still do rather well: disciplined capital allocation and operational excellence. It buys stagnating digital businesses — often 20 to 25-year-old internet brands with loyal user bases — cuts costs aggressively, injects AI and centralized engineering, and turns them profitable. Think of it as Constellation Software for consumer internet, executed with an Italian private equity mentality.
My investment case in one paragraph: The business model is genuinely one of the most interesting listed in years, and I have followed the company for a while. But at roughly 55x my adjusted 2026 earnings estimate and with $4.4 billion of debt on the balance sheet, the stock prices in flawless execution. This is a watchlist stock — and there is a cheaper back door into the story via Tamburi Investment Partners, which I hold indirectly. Let me walk you through it.
1. Product, Business Model, Brand and Moat
What does Bending Spoons actually do?
Bending Spoons is a hybrid between a software company and a private equity firm. It acquires established digital products that have stopped growing but still have healthy market positions and active users. Unlike classic PE, however, Bending Spoons does not flip these assets. It holds them permanently, rebuilds the technology, optimizes pricing and monetization — and then uses the cash flows to buy the next target.
The portfolio reads like a walk through internet history: AOL (yes, that AOL — email, news portal, search), Vimeo(video hosting, formerly listed), Evernote (note-taking), Eventbrite (event ticketing, formerly listed), WeTransfer (file sharing), Meetup, Brightcove (enterprise video, formerly listed), StreamYard (live streaming for creators), komoot(outdoor route planning — very popular here in Germany), Harvest (time tracking), Remini (AI photo enhancement, one of their original in-house successes) and Tractive, the Austrian GPS pet tracker.
As of March 2026, the group counted over 500 million monthly active users and more than 9 million paying subscribers, up from 111 million MAUs and 3 million payers at the end of 2023. In the German transcript I quoted older figures of one billion registered users and 7 million payers — the F-1 filing numbers above are the ones to work with.
How do they earn money?
Predominantly subscriptions and, in the case of AOL and Vimeo, advertising and enterprise contracts. The playbook after each acquisition is remarkably consistent: reduce headcount drastically (often 50–80% of the acquired team), migrate the product onto centralized Bending Spoons infrastructure, raise prices for the loyal core user base, and modernize the product with AI features. The productivity numbers are staggering: revenue per full-time employee rose from $1.12 million in 2023 to $2.57 million in 2025. The whole group runs on roughly 2,200 employees.
Brand and Moat
The moat is not in the individual brands — Evernote faces AI-native competitors, Vimeo fights YouTube — but in the acquisition machine itself. Bending Spoons has built proprietary playbooks, shared technology infrastructure, and a data-driven M&A process with a pipeline of reportedly over 1,000 targets. As one VC investor put it, traditional PE firms cannot replicate this because they don’t write code. That combination of engineering depth and buyout discipline is rare, and it compounds: every acquisition makes the platform more efficient for the next one. This is the same structural advantage that made Constellation Software a 100-bagger — the question is whether it works as well in consumer internet, where products decay faster than vertical market software.
2. Market
The addressable market is enormous and, in a strange way, growing every year: the pool of aging digital businesses. Thousands of software and consumer internet companies founded between 1995 and 2015 are now mature, no longer growing fast enough for venture capital, too small or too unloved for big tech, and often trading at depressed SaaS multiples. The AI-driven derating of legacy SaaS valuations in early 2026 — which frightened public market investors — is, from a buyer’s perspective, a gift. Management explicitly said after the IPO that this is a great moment to deploy capital.
The market is largely free from political intervention (consumer software faces far less regulatory scrutiny than fintech or healthcare), and the subscription-heavy revenue mix makes the business less cyclical than advertising-dependent models — although AOL does bring meaningful advertising exposure. The real constraint is not market size but capital: this model needs continuous access to debt and equity funding, which is precisely why the IPO happened.
3. Culture and Management
This is where the story gets genuinely compelling. The four co-founders — CEO Luca Ferrari, Matteo Danieli, Luca Querella and Francesco Patarnello — failed with their first startup, Evertale, a machine-learning diary app, back in 2013. Their conclusion from that failure shaped everything: success from zero to one is heavily luck-dependent, and there is no perfect correlation between operator talent and startup outcomes. So instead of gambling on product-market fit, they decided to buy product-market fit and apply operational excellence to it. They call it minimizing luck.
I find this deeply refreshing. In Silicon Valley, nobody looks at costs until they have to; in the European second tier, cost discipline is a survival skill — and Bending Spoons has turned it into an offensive weapon. The founders retained significant control through the IPO, the entire company was flown to New York for the listing day, and the F-1 contains a chapter titled “AI before it was cool.” This is founder-led, long-term oriented, slightly contrarian — exactly the management profile I look for. The pre-IPO cap table was also high quality: Baillie Gifford held 15%, Cox Enterprises 9.3%, and Italian holding Tamburi Investment Partners around 2.85%.
The culture has a dark side that one must acknowledge: the layoffs are brutal, and the Vimeo restructuring in particular drew heavy criticism. Whether you view this as necessary surgery or reputation risk is partly a values question — but as an analyst, I note that it works financially.
4. Financials and Margins
The reported growth is spectacular — but almost entirely acquired:
Revenue: $387 million (2023) → $671 million (2024) → $1.31 billion (2025)
Q1 2026: $601 million revenue, +132% year-over-year, with $27.5 million net income
2025 net result: a loss of $112 million, after net income of $89 million in 2024
The 2025 loss is not operational weakness but accounting: purchase price amortization, restructuring charges and financing costs from the AOL, Vimeo and Eventbrite acquisitions flow through the P&L, very similar to what we know from Constellation Software. Underlying, the acquired assets are being pushed to EBITDA margins that standalone management teams never achieved. The Q1 2026 run-rate suggests around $2.4 billion in annualized revenue.
Organic growth, however, is modest — I estimate low single digits across the portfolio, and some assets like Evernote are probably shrinking. This is the crucial analytical point: Bending Spoons is a capital allocation compounder, not a growth company. Reported growth will always be a function of deal flow.
The balance sheet carries roughly $4.4 billion in debt against about $1 billion in net IPO proceeds. Leverage is manageable given the cash-generative portfolio, but it means the equity is a leveraged bet on execution.
5. Valuation: The Sum-of-the-Parts View
Because the group is a collection of very different assets, a sum-of-the-parts analysis is more instructive than a single multiple. Below is my rough SOTP based on estimated revenue splits and what I consider fair standalone multiples (my estimates, not company disclosures):
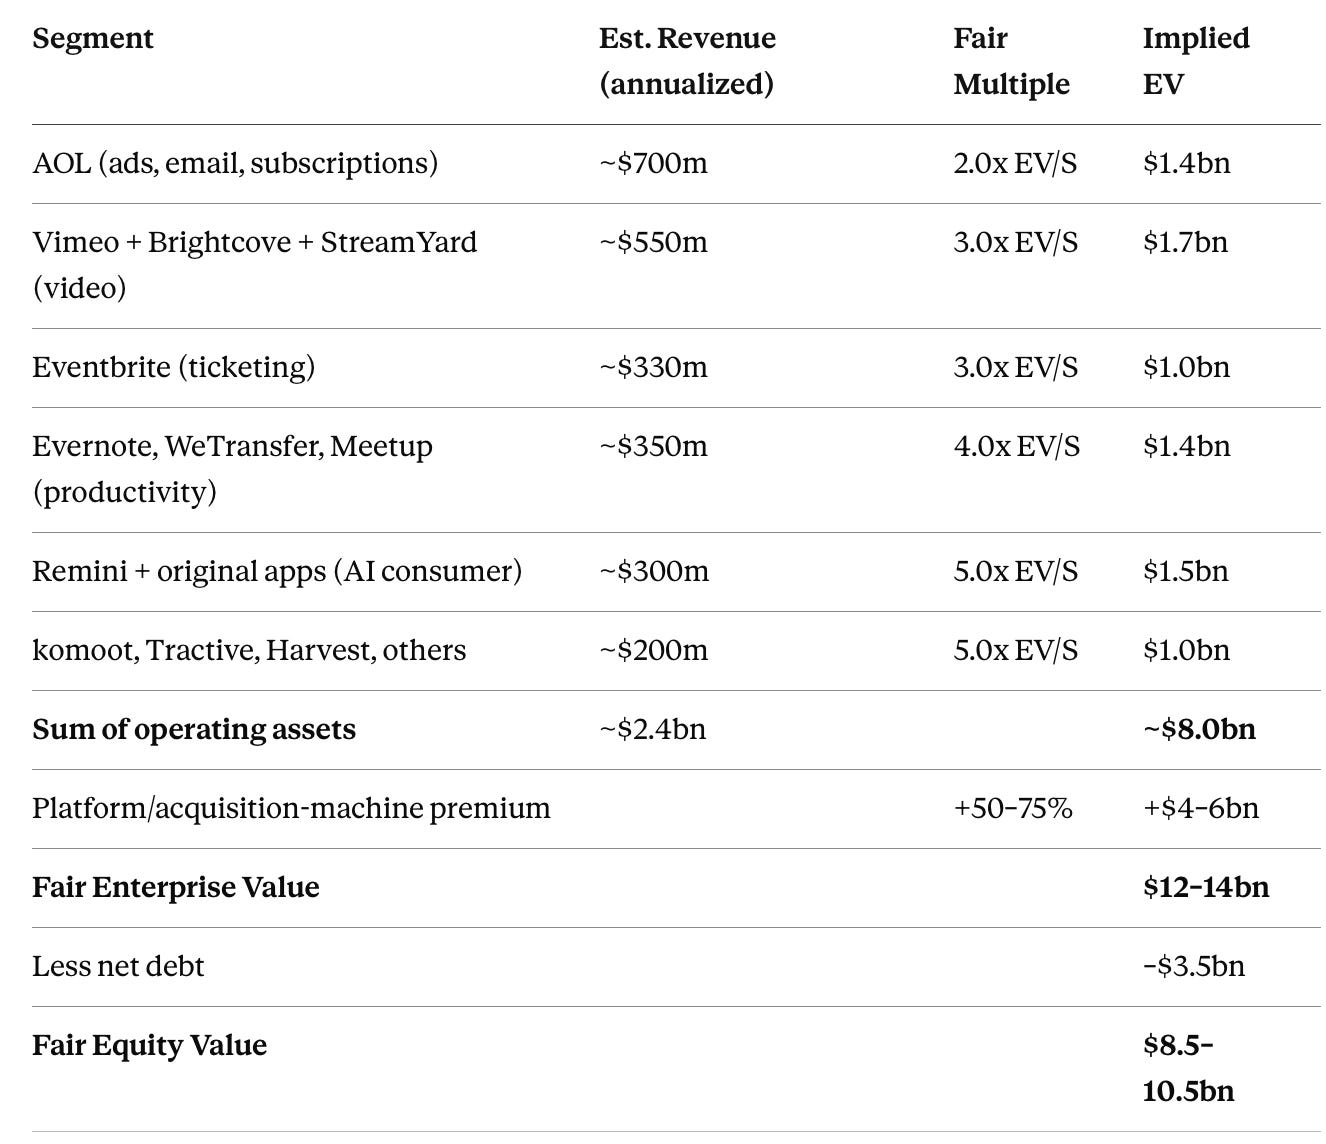
Against a current market cap of ~$22.7 billion, even a generous SOTP that pays a substantial premium for the acquisition platform suggests the stock trades at roughly double its fair value. The market is effectively paying $10+ billion for future deals that have not happened yet.
My Fair-PE cross-check tells the same story. Taking an adjusted (cash) EPS of around $0.65 for 2026 — stripping out amortization and one-off restructuring — the stock trades at roughly 55x earnings at $36. Even applying my fair P/E of 29, which is already generous and reflects the quality of the capital allocation machine, and rolling forward three years of EPS growth to perhaps $1.10–1.30 by 2028, I arrive at a fair value of $32–38 per share in 2028. From today’s price, that implies an expected return of roughly zero percent per annum. Not a margin of safety — a margin of hope.
The Tamburi back door. There is, however, an indirect way to own Bending Spoons at a discount: Tamburi Investment Partners (TIP), the Milan-listed holding company, retained approximately 2.45% of Bending Spoons after selling a small slice into the IPO for about €58 million. The IPO lifted TIP’s NAV by roughly €380 million, about 15%, and the Bending Spoons stake now represents one of the largest positions in the portfolio alongside quality Italian mid-caps like Interpump, Moncler, SeSa, OVS and Amplifon, plus unlisted gems such as Chiorino, Azimut Benetti and Alpitour. TIP trades at a 30–39% discount to NAV, which analysts rightly call excessive. So you can buy Bending Spoons exposure at roughly two-thirds of market price, bundled with a solid Italian Mittelstand portfolio and Giovanni Tamburi’s track record. I hold TIP indirectly via my Wikifolios, and this remains my preferred vehicle at current prices.
6. Latest News and Earnings
The news flow since listing has been dense. The IPO priced above range at $29 on July 1, raising $1.68 billion with Goldman Sachs, JPMorgan and Allen & Co. as bookrunners, and closed its first session at $40.50 before settling around $36. CEO Luca Ferrari emphasized that the listing primarily provides acquisition firepower and highlighted enormous AI-driven productivity gains internally. Q1 2026 showed revenue of $601 million, up 132% year-over-year thanks to the AOL, Vimeo and Eventbrite consolidation, with a return to positive net income of $27.5 million. Management confirmed the pipeline of over 1,000 potential targets and signaled that depressed SaaS valuations make this an attractive moment to deploy the fresh capital. A curiosity worth noting: tokenized BSP shares launched in parallel on crypto platforms — a sign of how much retail attention this IPO attracted, which historically is not a bullish contrarian signal.
On the Tamburi side, Intermonte raised its target price to €14.60 from €11.80 after the IPO, and Giovanni Tamburi stated that the partial sale was merely a market signal — over 80% of the position is being kept.
7. Conclusion: A Wonderful Machine at the Wrong Price
Bending Spoons is exactly the kind of business I love to study: founder-led, contrarian, operationally brilliant, building a repeatable capital allocation machine in a structurally growing pond of neglected digital assets. It is Constellation Software translated into consumer internet, with an Italian accent and better engineering.
But at ~$36 per share and ~$22.7 billion market cap, I am being asked to pay roughly twice my sum-of-the-parts fair value and 55x adjusted earnings for a business whose organic growth is in the low single digits. My Fair-PE framework spits out an expected annualized return near zero over three years. That is not a price I pay, however much I admire the model.
My playbook: BSP goes straight onto the watchlist. If the stock corrects 30–40% — as post-IPO stocks so often do once lockups expire and the excitement fades — it becomes genuinely interesting somewhere in the low-to-mid $20s. Until then, Tamburi Investment Partners at a 30%+ NAV discount is the smarter way to own a piece of this story, and I do so indirectly via my Wikifolios. Either way: learn this company. We will hear a lot more from Bending Spoons — they are just getting started with their shopping list.
Philipp Haas is fund advisor of the Haas Invest4 Innovation Fund and founder of investresearch.net.