

Introduction: The Watchlist Stock That Finally Came to Me
Every investor has a handful of companies they admired for years but never owned, simply because the price was never right. Atlassian has been exactly that stock for me. When I first analyzed it in depth, the company was a roughly $35 billion market cap hyper-growth darling: not profitable on a GAAP basis, trading at a valuation that implied around $1,500 of market cap for every single addressable software developer on the planet – developers Atlassian had not even won as customers yet. My verdict back then was clear: great company, wonderful viral business model, but fundamentally far too expensive. A good company is not automatically a good stock if you pay any price. It went on the watchlist.
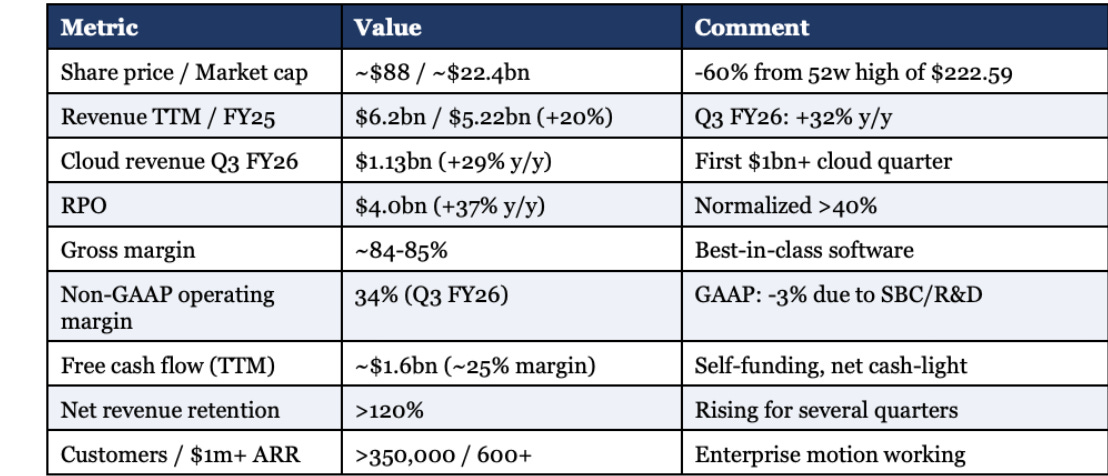
Fast forward to mid-2026, and the situation has inverted in a way that even I find remarkable. Atlassian’s revenue has more than doubled since my first analysis, the company just printed 32% year-over-year revenue growth in its latest quarter, free cash flow is running at roughly $1.6 billion per year – and yet the stock has collapsed from a 52-week high of $222 to around $88, a drawdown of about 60%. The market cap today, at roughly $22 billion, is lower than it was when the company was a fraction of its current size. The reason is the so-called “SaaSpocalypse”: the market’s fear that AI agents will eat seat-based software. That fear is not irrational, but in Atlassian’s case I believe it is heavily overdone – and it has created exactly the kind of contrarian GARP setup I look for. The investment case in one sentence: a founder-led, cash-generative platform with a net revenue retention above 120%, growing revenue at 20-30%, trading at roughly 14x forward Non-GAAP earnings and 3.5x sales.
1. Product, Business Model, Brand and Moat
Atlassian sells software that makes teams work better together – the ticker TEAM says it all. The core franchise is Jira, the de-facto standard for agile software development and project tracking, flanked by Confluence (knowledge management and wikis), Jira Service Management (IT and enterprise service management), Trello (lightweight, consumer-style task boards), Bitbucket (code hosting), Loom (asynchronous video) and, increasingly important, Rovo – Atlassian’s AI layer with search, chat and autonomous agents built on top of the so-called Teamwork Graph, the accumulated data about how an organization actually works.
What always fascinated me about Atlassian is the distribution model. The company grew for years almost without a classic salesforce. Developers are a viral community: when one engineer loves a tool, she carries it to her next project, her next employer, her open-source community. Atlassian deliberately kept entry prices low – historically single-digit dollars per user per month – and let the product sell itself. This land-and-expand flywheel is still working: the company now serves more than 350,000 customers, and net revenue retention sits above 120%, meaning the existing base alone grows spending by over 20% per year through more seats, more products and higher tiers.
The business model is classic cloud subscription with per-seat pricing, increasingly bundled into “Collections” (Teamwork Collection, Strategy Collection, Service Collection) that package multiple products together with generous Rovo AI credits. This bundling is smart: Teamwork Collection customers consume more than three times the Rovo credits per user and run more than twice as many AI agents – the AI product deepens the platform lock-in rather than sitting beside it. Pricing power remains substantial; like Netflix in its early years, Atlassian has raised prices regularly and the low absolute cost per seat relative to a developer’s salary means customers rarely churn over price.
The moat rests on three pillars: first, extremely high switching costs – Jira instances contain years of workflows, tickets and institutional memory; ripping them out is a career risk for any IT manager. Second, an ecosystem of thousands of marketplace apps and solution partners that competitors cannot replicate quickly. Third, and increasingly, the Teamwork Graph data asset, which makes Atlassian’s AI answers contextual and cheaper to compute. I also always liked the management’s strategic discipline: years ago, when their chat products HipChat and Stride were losing against Slack, Atlassian did not burn money on a hopeless fight – they sold the products to Slack, took an equity stake, and refocused. That capital allocation mindset is rare.
2. Market: From Developer Niche to the “System of Work”
My biggest concern in my original analysis was market size. Back then, Atlassian framed its opportunity around roughly 23 million software developers worldwide – a valuable but ultimately limited community, and I argued that a $35 billion valuation for a top-three tool in a niche was aggressive. This objection has aged interestingly. The developer population has grown, but more importantly, Atlassian has successfully broadened its addressable market far beyond developers: Jira Service Management competes with ServiceNow in IT service management, Confluence and Trello address general knowledge workers, and the “system of work” positioning targets the connective tissue between business and technology teams in every large organization. The enterprise push is visible in the numbers: remaining performance obligations of $4.0 billion, up 37% year-over-year, and more than 600 customers spending over $1 million per year, with names like Siemens Energy, Rheinmetall, the BBC and Wayfair deepening their commitments recently.
The market itself is structurally growing – collaboration, DevOps and service management software all compound at double-digit rates – and is essentially free from political intervention; nobody regulates ticketing software. Cyclicality exists indirectly: per-seat pricing means Atlassian’s growth breathes with tech headcount. The 2022-2024 tech layoff cycle slowed seat expansion, and the current AI-driven uncertainty about future white-collar and developer headcount is precisely what the bears extrapolate. Competition is real – Monday.com, Asana, Linear, Notion, GitHub and Microsoft all overlap somewhere – but nobody matches Atlassian’s combination of developer credibility, enterprise depth and price point.
3. Culture and Management: Founders Who Adapt
Atlassian remains founder-led, which is one of my most important quality criteria. Mike Cannon-Brookes, who co-founded the company in Sydney in 2002 with a credit card and a beer budget, is still CEO and a major shareholder; co-founder Scott Farquhar stepped back from the co-CEO role in 2024 but remains on the board. Together the founders still control the company through super-voting shares – you invest alongside them, not instead of them. The culture (”Open company, no bullshit”) consistently earns strong employee ratings and has produced an unusual capacity for reinvention: from server licenses to cloud, from developer tools to enterprise platform, and now to AI.
What impressed me most recently is the March 2026 restructuring. Instead of hiding behind past success, Cannon-Brookes publicly acknowledged that the bar for software companies has gone up and announced a decisive reorganization: restructuring to self-fund investments in AI and enterprise sales, an accelerated path to sustained GAAP profitability, and dedicated, accountable leadership teams per Collection. This is exactly the long-term, owner-like behavior I want to see when an industry’s rules change. Many founder-CEOs fall in love with their old playbook; these founders are rewriting theirs.
4. Financials, Margins and Recent Developments
The growth track record is exceptional. Fiscal year 2025 (ending June) revenue reached $5.22 billion, up about 20%, and fiscal 2026 has accelerated: quarterly revenue climbed from $1.43 billion to $1.59 billion to $1.79 billion in Q3 FY26 (March quarter), the latter up 32% year-over-year. Trailing twelve-month revenue now stands at roughly $6.2 billion, with annual run-rate revenue having crossed $6 billion. Cloud revenue, the strategically decisive segment, delivered its first $1 billion quarter and accelerated to 29% growth, driven by cross-selling of the Teamwork Collection and continued seat expansion.
The margin picture requires the differentiated look I always insist on. Gross margin is a spectacular 84-85% – this is software royalty economics. On a GAAP basis Atlassian still reports a small operating loss (about -3% margin) and a trailing net margin of roughly -3.5%, almost entirely a function of very high stock-based compensation and aggressive R&D spending of over 30% of revenue. The economically relevant metrics look very different: non-GAAP operating margin reached 34% in the latest quarter, non-GAAP EPS came in at $1.75 versus $0.98 expected – a massive beat – and levered free cash flow runs at about $1.6 billion over the trailing twelve months, a FCF margin of roughly 25%. Return on equity is optically negative due to the GAAP loss and a balance sheet shaped by buybacks; I therefore anchor on FCF and non-GAAP operating margin instead, the same way I refuse to judge banks by EBITDA. One caveat honesty demands: Q3 included roughly $50 million of pulled-forward data center term-license revenue, so the underlying growth rate is closer to the mid-20s than to 32% – still excellent.
5. Valuation: The Fair PE Bridge
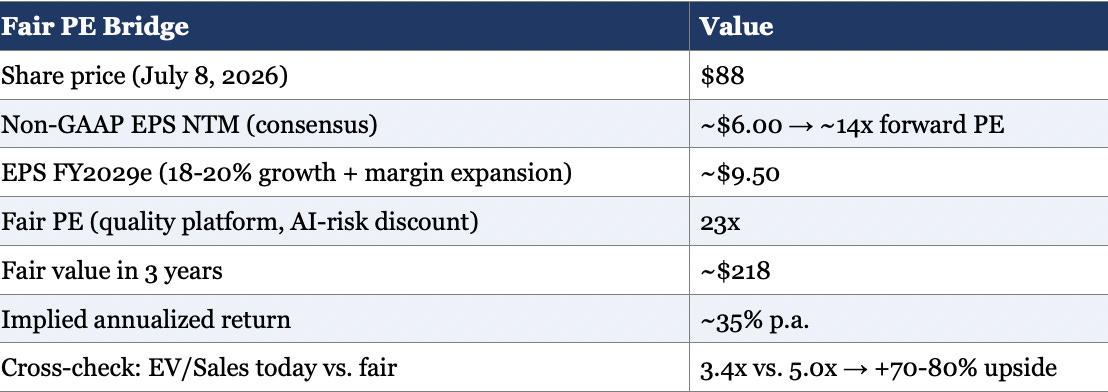
As always, my anchor is the Fair PE model: what multiple does the quality of the business deserve, applied to realistic earnings three years out? For a founder-led platform with 85% gross margins, 120%+ net revenue retention, a genuine moat and 20%+ growth, I consider a fair PE of 22-24 appropriate – deliberately below the 30-35x such assets commanded in the ZIRP era, reflecting AI disruption risk, but well above a market multiple, because this is emphatically not an average business.
Consensus expects roughly $6 of non-GAAP EPS over the next twelve months, which puts the stock at only about 14x forward earnings – a multiple normally reserved for mature, slow-growth software. Assuming revenue compounds at a conservative 18-20% and the announced march toward GAAP profitability lifts margins, EPS of around $9.50 by FY2029 is achievable without heroic assumptions. Applying a fair PE of 23 yields a three-year target of roughly $215-220 – coincidentally right back at the old high – implying approximately 35% annualized return potential from $88. The cross-check via sales-based valuation points in the same direction: the enterprise value of about $21.4 billion equals just ~3.4x trailing and roughly 2.8x forward revenue. I regard a fair EV/Sales ratio of 5 as justified for this quality of recurring revenue, which alone implies upside of 70-80% even before further growth. When the Fair PE and the fair EV/Sales models independently signal 30%+ annual return potential, my attention is fully awake. I normally use GAAP-Earnings, but I think the Stock based compensation will come down meaningfull the next quarters und the market underestimates the scalability of the business model.
6. Risks: Why Is the Stock So Cheap?
A 60% drawdown in a growing business always has a narrative behind it, and it deserves to be taken seriously. The dominant fear is existential: if AI coding agents write more and more software autonomously, do companies need fewer developers – and therefore fewer Jira seats? And could AI-native challengers rebuild project management from scratch, making the incumbent’s per-seat model obsolete? This “SaaSpocalypse” thesis hammered the entire application software sector, and Atlassian, as the quintessential per-developer-seat business, was hit hardest. I do not dismiss this risk: it is the reason my fair PE is 23 and not 32.
The further risk list: stock-based compensation remains high and dilutive, and GAAP profitability is still a promise rather than a fact. Data center license revenue is lumpy – the $50 million Q3 pull-forward will unwind and could make the Q4 report on August 3 optically messy, especially as management has deferred FY2027 guidance to that date. Competition from Monday.com, Notion, Linear, GitHub and ServiceNow is intensifying at both the low and high end. Some insider selling and a string of analyst price-target cuts (targets now range all the way from $95 to $295 – rarely have I seen such dispersion) show how divided the professional community is. But this dispersion is precisely why the opportunity exists: when nobody agrees on what a business is worth, the price is set by fear, not by arithmetic. My counterargument to the seat-decline thesis is empirical: Atlassian’s own AI customers are growing ARR at twice the rate of non-AI customers. So far, AI is expanding Atlassian’s wallet share, not shrinking it – software may increasingly be written by agents, but those agents still need a system of record for work, and the Teamwork Graph is exactly that.
7. Latest News and Earnings
The Q3 FY26 report on April 30 was, frankly, one of the strongest software prints of the season: revenue of $1.79 billion beat consensus by 14%, non-GAAP EPS of $1.75 beat by almost 80%, and the stock jumped around 30% in relief – before giving much of it back as the sector-wide AI angst returned. Rovo has surpassed 5 million monthly active users, AI credit consumption is compounding at more than 20% month-over-month, and management reported meaningful competitive displacement in service management. At the Team ‘26 conference, Atlassian committed to enhanced disclosures including historical subscription ARR to help investors see through the data center timing noise. Alongside the March restructuring toward GAAP profitability, the company was also named a Leader in Gartner’s inaugural Magic Quadrant in its category. The next catalyst is the Q4 and full-year report expected on August 3, together with the first FY2027 guidance – realistically the moment the market decides whether the de-rating was a gift or a warning.
8. Conclusion: The Second Chance I Was Waiting For
Years ago I concluded that Atlassian was a wonderful company at an impossible price, and I let it go. Today the company is more than twice as large, more profitable in cash terms, more diversified beyond its developer niche, has a credible and already-monetizing AI product – and costs a third less in absolute market cap than it did back then. The investment case rests on three pillars: first, AI as an opportunity rather than only a threat – Rovo sits on proprietary workflow data, is priced through consumption-based credits on top of seats, and demonstrably accelerates customer spending. Second, an enormously scalable business model with 85% gross margins, where the announced cost discipline and the shift of the last GAAP losses into profit can produce years of 20%+ earnings growth on 18-20% revenue growth. Third, a valuation – 14x forward earnings, 3.4x EV/Sales – that prices in stagnation for a business that just grew 32%.
Of course, the AI seat-risk debate will not be settled by one quarter, and the stock will remain volatile around the August report. But my investment philosophy has always been to buy quality when the crowd is scared, not when it is euphoric. At $220 last summer, Atlassian was a momentum stock priced for perfection. At $88, it is a contrarian GARP investment with a Fair PE bridge pointing to roughly 35% annualized return potential. The great company has, in my view, finally become an interesting stock – and this time I did not just put it on the watchlist.
Disclaimer & Conflict of Interest
This article reflects the personal opinion of the author and is provided for informational and educational purposes only. It does not constitute investment advice, a recommendation, or an offer to buy or sell any security. All figures are based on publicly available information believed to be reliable at the time of writing but are not guaranteed to be accurate or complete. Equity investments involve substantial risk, including the possible loss of the entire capital invested; past performance is no indication of future results. Every investor must conduct their own research and, where appropriate, consult a licensed financial advisor before making investment decisions.
Conflict of interest: Atlassian (TEAM) is part of the portfolio of the cost-efficient Haas Invest4 Innovation investment fund (invest4.net), which is managed by the author. The author and the fund may buy or sell shares of the company at any time without prior notice.